World news and discussion on TalkFuse.
Pension reforms leave some older retirees £53 a week worse off
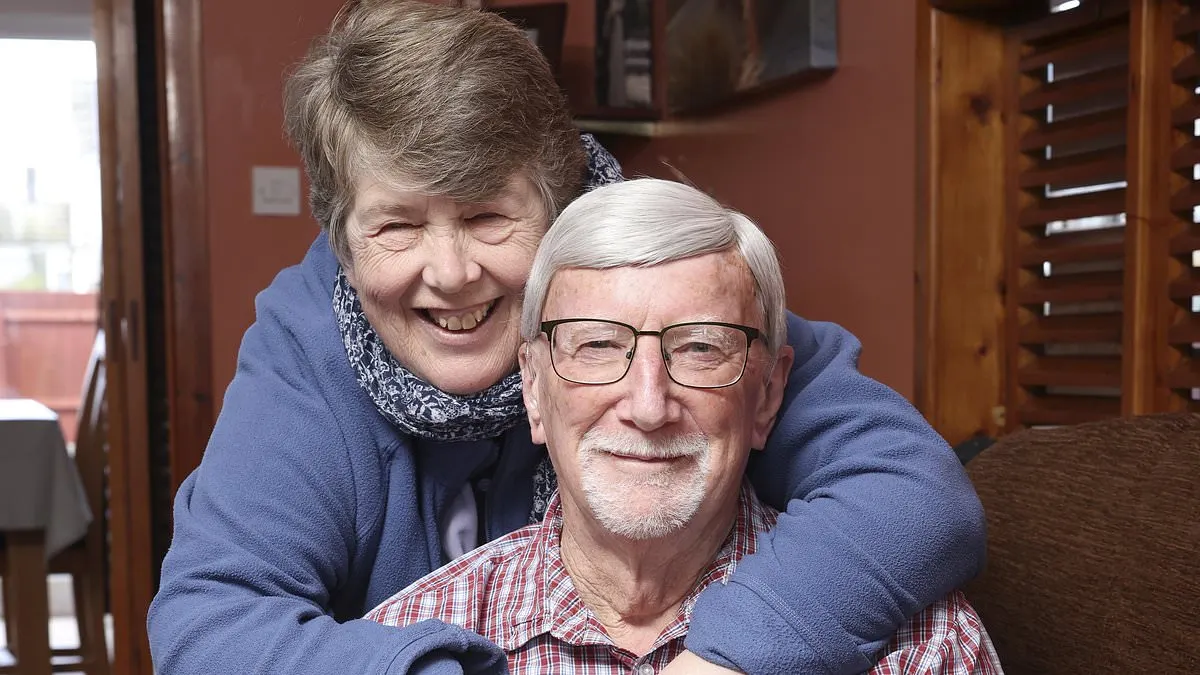
Ron Holdway, 82, receives £53 a week less state pension than his wife Lesley, despite having paid National Insurance for 13 more years. Their case highlights how the 2016 pension reforms created different outcomes for people who reached state pension age before and after the change.
The old system combines a basic pension, currently £184.90 a week, with possible earnings-related additions; the new system pays up to £241.30 a week, usually requiring 35 qualifying years. Lesley qualifies for the full new pension, while Ron, who was self-employed and could not contribute to the old earnings-related top-ups, receives less. The article says the gap could amount to about £55,000 over 20 years, and that equal percentage increases under the triple lock add more cash to Lesley’s larger pension.
In short
- Pension rules changed in 2016, creating different outcomes for older and newer retirees.
- Lesley receives £53 more a week than Ron despite 13 fewer NI years.
- The triple lock increases the cash gap because her pension is larger.
Steelman: both sides, in good faith
The strongest fair case each way — we don't pick a winner.
The case for
The reforms aimed to make the state pension clearer and more generous for many people, while supporting its long-term affordability. A transition between systems inevitably leaves people with different entitlements, and those who built up rights under the previous rules may reasonably expect those rights to be honoured rather than recalculated under a new formula.
The case against
The case for reform is that people with similar working lives should not face sharply different pensions simply because they reached pension age on different dates or had limited access to earnings-related contributions. A system that leaves some long-serving contributors substantially worse off can be seen as unfair, and equal percentage uprating widens the cash gap between people on lower and higher pensions.
Explained simply
The state pension is a regular payment from the government, with the amount depending on a person’s age and National Insurance record. Before April 2016, it was made up of a basic pension and, for some people, extra payments linked to their earnings.
People who reached state pension age from April 2016 are generally covered by a newer system, which pays a higher full rate but usually requires 35 qualifying years of National Insurance. The transition means people of similar ages can receive different amounts, depending on when they qualified and their work and contribution histories.
Self-employed people could build up the basic pension under the old system but generally could not pay into its earnings-related top-ups. Annual increases under the triple lock apply to pension rates, so the same percentage rise adds more money to a higher pension; these rules shape how differences between retirees can persist or grow.
Read the full article at the source →
Originally published by Daily Mail as “Revealed: The great state pension injustice that leaves older pensioners worse off. Here’s how to tell if YOU are a victim”.