Firmus float falters as investors question its A$44bn valuation
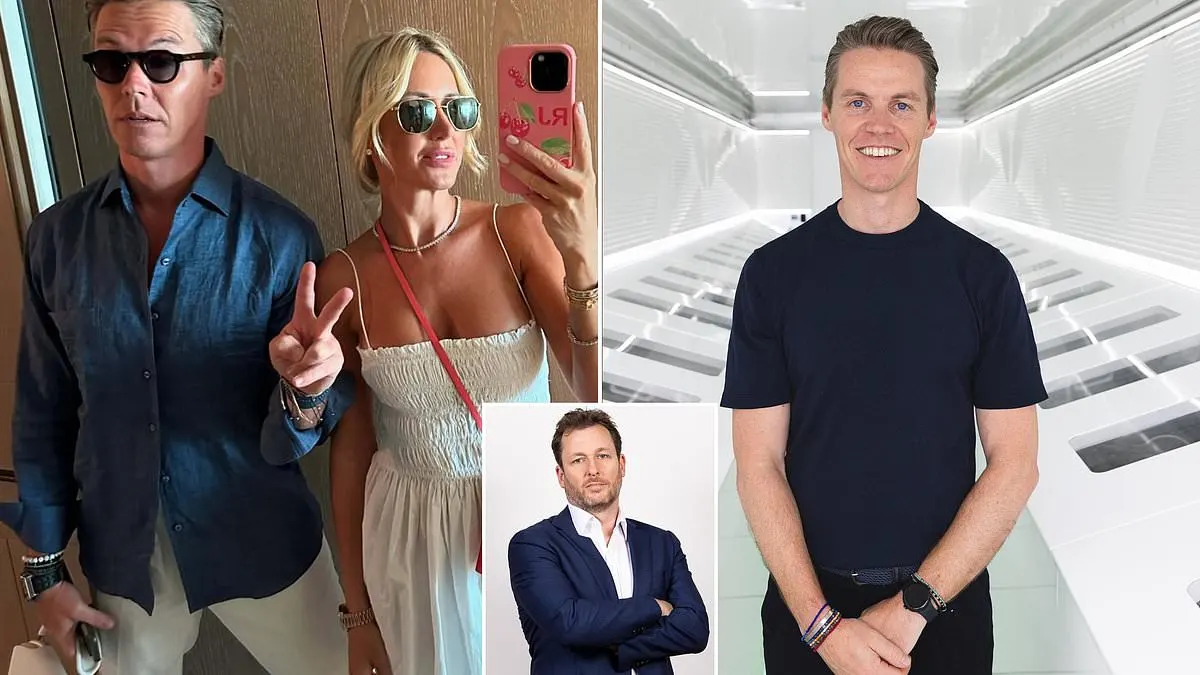
Oliver Curtis’s attempt to float data-centre company Firmus collapsed after investors balked at a proposed valuation of about A$44 billion. The article argues that the failed float exposed legitimate business concerns, but should not automatically define Curtis’s efforts to rebuild his life after prison.
Curtis was convicted in 2016 of conspiring to commit insider trading, involving 45 trades and about A$1.4 million in illegal profits, and served a year in prison. Firmus, co-founded in 2019, has developed computing and cooling technology, attracted Nvidia as an investor and secured customers including Meta and OpenAI, but had only two operational sites and substantial expansion still ahead. The proposed sale of existing shares on the first trading day and the withdrawal of development partner CDC Data Centres also raised questions; the article says Curtis must now demonstrate that the business can deliver.
- Firmus withdrew its proposed A$44 billion float after investor resistance.
- The company has customers and backers, but limited operating sites.
- Curtis’s next steps will shape whether he earns renewed trust.
New here? Start with this
Firmus is a data-centre technology company co-founded by Oliver Curtis that attempted to float with a proposed valuation of around A$44 billion. Investors rejected the proposal and the listing has collapsed.
Curtis was convicted in 2016 of conspiring to commit insider trading and served a year in prison. The collapse of the Firmus float comes as Curtis has been working to rebuild his business career.
Firmus has developed cooling and computing technology for data centres and counts Nvidia among its investors, with customers including Meta and OpenAI. However, the company has only two operational sites and substantial further expansion ahead, and the failed float has raised questions about whether it can deliver.
Both sides, in good faith
The strongest fair case each way — we don't pick a winner.
The case for
Firmus possesses legitimate technology that has attracted major investors including Nvidia and customers such as Meta and OpenAI, suggesting genuine commercial potential. A failed IPO reflects market conditions and valuation disagreements rather than fundamental business flaws, and many successful companies have faced setbacks at float stage. Curtis has served his sentence for a conviction a decade ago and, like anyone seeking redemption, should be judged by his current conduct and whether the underlying business has genuine merit, not by using business failure as a proxy for moral character.
The case against
The company demonstrated material readiness issues—only two operational sites despite nearly a decade of existence, substantial unproven expansion plans, and the unexpected withdrawal of development partner CDC Data Centres—that justified investor scepticism about the A$44 billion valuation. Curtis's 2016 conviction for insider trading reflects a pattern of poor judgment about rules and ethics in high-stakes scenarios, which raises legitimate concerns about whether the aggressive float structure and valuation represented sound business practice or overreach. For investors and the public, financial credibility is inseparable from character history when substantial capital is at stake.
Read the full article at the source →
Originally published by Daily Mail as “Sneering critics want Oliver Curtis forever defined by his jail stint. Tall poppies of Australia, here’s a newsflash for you: PVO”.