California Democrat ‘deeply disappointed’ after Newsom vetoes reparations tax break
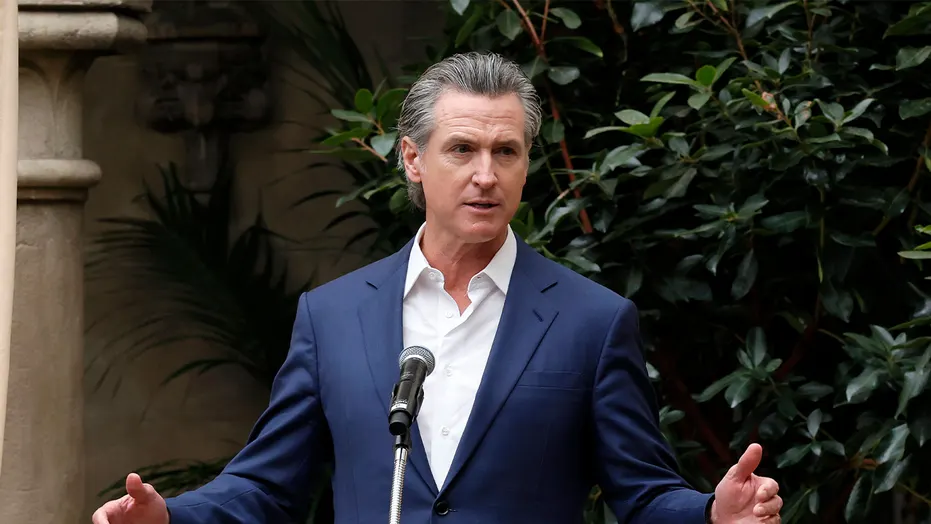
California Governor Gavin Newsom vetoed a bill that would have exempted future reparations payments from state income tax, prompting Democratic Assemblymember Tina McKinnor to say she was “deeply disappointed”. Newsom said he supported efforts to address the harms of slavery but that the exemption’s scope and potential cost were unclear.
The proposed exemption would have applied to qualifying reparations payments or benefits received from 2028 through 2032, including grants, debt forgiveness and trust distributions. Newsom said the measure should be considered through the annual budget process. He signed a separate bill requiring certain large companies to search for and disclose records of slavery-era transactions, with first sworn reports due by January 2029 once the law is funded.
- Newsom vetoed a proposed tax exemption for reparations.
- The bill covered qualifying payments from 2028 to 2032.
- A separate law requires large firms to disclose slavery-era records.
New here? Start with this
Reparations are payments or other measures intended to address lasting harms caused by slavery and its effects. In California, a state task force has examined those harms and proposed ways to respond, including financial support for eligible people.
Tina McKinnor is a Democratic member of California’s state Assembly, which makes laws for the state. Gavin Newsom is California’s governor; he can sign bills into law or veto them.
The proposed tax exemption concerned whether future reparations benefits would count as income for state tax purposes. The debate matters because the tax treatment could affect how much recipients keep, while the state would need to assess the measure’s cost and scope.
Both sides, in good faith
The strongest fair case each way — we don't pick a winner.
The case for
Exempting reparations from state income tax could help ensure recipients retain the full value of payments intended to address harms caused by slavery. Supporters may argue that the bill gave recipients and programme administrators clarity ahead of payments planned from 2028, and that tax treatment should not diminish reparative benefits.
The case against
Newsom’s concern is that the exemption’s scope and cost were not yet clear, making it difficult to judge its effects on state revenues or how it would interact with different forms of reparations. Considering the issue through the annual budget process could allow lawmakers to assess those consequences alongside the design and funding of the payments.